
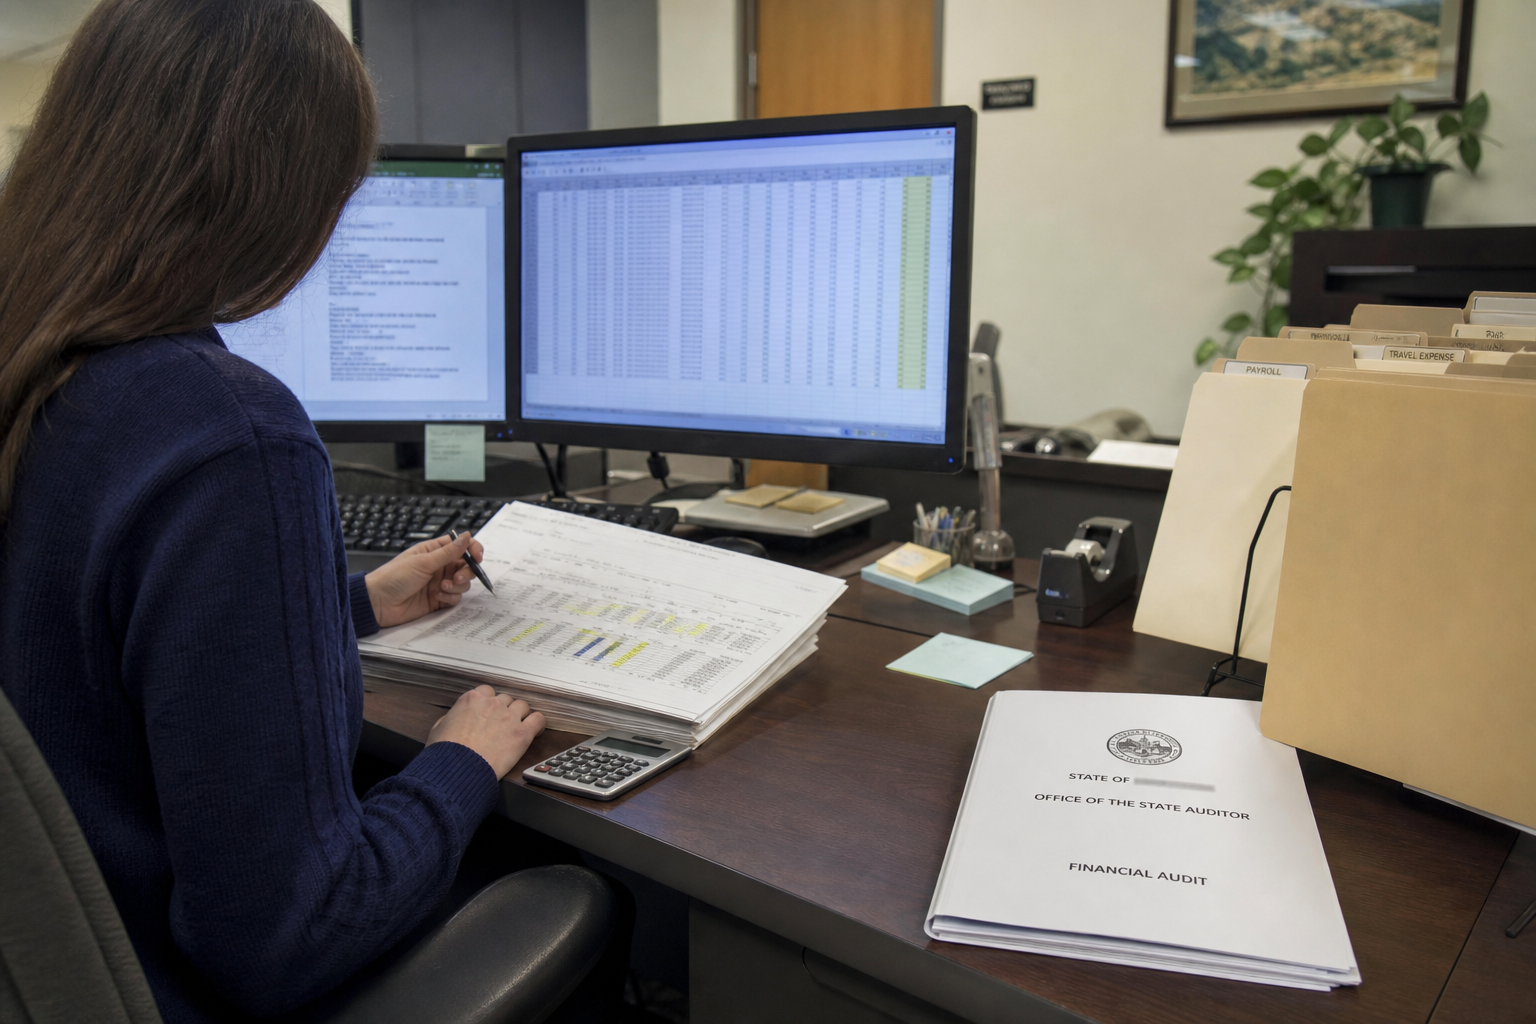
The Audit Gap Nobody Talks About
States receive hundreds of billions in federal grant money every year. Housing programs. Transportation. Education. Social services. The money arrives with conditions attached—spend it this way, report these numbers, follow these rules. Then something happens that should not happen: the audits designed to verify compliance don't work the way they should.
This is not a secret. The federal government's own Inspector General offices document it. State auditors file reports on it. But the gap between what the audits are supposed to catch and what they actually catch keeps widening, and the people signing off on the grants keep moving to the next line item.
How States Sidestep Accountability
Start with the basic structure. When a state receives a federal grant, it agrees to follow federal rules. Some states do. Some states follow the rules in ways that technically satisfy the letter while dodging the purpose. Some states simply move money around and hope nobody notices.
The auditing process should prevent all three. A state agency gets a grant. It spends the money. An auditor—either internal, or brought in from outside—reviews the spending. The auditor checks the receipts. Verifies the expenses matched the grant conditions. Confirms the money went where it was supposed to go. Reports any problems. Done.
Except it is not done. Not most of the time.
Many states lack the staffing to conduct comprehensive audits of federal grants. An auditor assigned to review a multi-million dollar housing program might have two weeks and no access to the underlying documentation. The state agency being audited controls the files. The auditor gets a summary. The agency says the money was spent correctly. The auditor signs off. The next grant comes through. The cycle repeats.
The Documentation Problem
Ask any state finance official how they track federal grant spending and you will get an answer about their accounting system. Ask them to produce the supporting documentation—the actual invoices, timesheets, contracts, and receipts that prove the money went where the grant required—and you will get a different answer. Many states cannot produce it fast. Some cannot produce it at all.
This is the real vulnerability. A grant says money must go to low-income housing. The state agency reports that it did. But did it? To know, you would need to see the actual contracts with the housing developers. The lease agreements with the tenants. The proof that the units were actually occupied by people meeting the income thresholds. The invoices for construction or renovation work. The sign-offs from inspectors. The records of how many people were actually served.
Most states do not maintain these records in a way that makes them retrievable. Some maintain them but do not preserve them long enough. Some agencies view the records as internal administrative documents and resist making them available for audit.
When Auditors Find Problems
When an audit does uncover something wrong—a contractor was paid without proper justification, or funds were diverted to an unauthorized purpose, or spending did not match grant requirements—the question becomes: what happens next? The answer varies wildly. Some states require immediate repayment. Some negotiate a settlement. Some classify the finding as a "questioned cost" and move on. The federal government can theoretically pull future grants, but that threat is rarely used. Too much political friction. Too much disruption to services. So the state negotiates, the auditor documents the finding, and the next grant cycle begins.
The problem multiplies across fifty states and thousands of grant programs. A housing grant here. A transportation grant there. A workforce development grant. A healthcare grant. Each one arrives with audit requirements. Each one has a different federal agency overseeing it. Each one has gaps in how thoroughly it is actually audited.
Who Bears the Cost
You do. If a state misuses federal grant money and the audit fails to catch it, that money is not recovered. It comes from your federal taxes. The same tax dollar that might have funded infrastructure in your district instead funds something else in another district, or simply vanishes into an agency's administrative overhead.
This is not theoretical. Year after year, federal audit reports flag the same patterns. Inadequate documentation. Insufficient staffing for audits. Weak enforcement when problems are found. States that have chronic issues with grant management continue to receive new grants, because the punishment for mismanagement would disrupt actual service delivery.
What Real Accountability Would Look Like
Start with documentation standards. Every grant should require that the state receiving it maintain supporting documentation in a standardized, retrievable format. Not summaries. Not agency reports. Actual evidence that money was spent according to the grant terms. Second, audits should be independent. States should not be able to audit their own federal grant spending. Third, consequences should matter. When an audit finds a problem, there should be a clear financial penalty to the state, not just a negotiated settlement that lets the agency off the hook.
None of this is complicated. It requires will, not innovation. Federal agencies already have the authority to demand it. Congress could require it. States could do it voluntarily if they actually wanted accountability rather than access to the money.
The Mark on Your Calendar
Your state is receiving federal grant money right now. Housing programs. Transportation projects. Education initiatives. Ask your state representative: where are the audits of this spending? Not the summary reports. The actual audits. Ask where the supporting documentation is kept. Ask what happens when an audit finds that money was misspent. Get answers before the next grant cycle, not after.
